When AI infrastructure ETFs and memory indicators move with a 90% correlation, it is more than a statistical curiosity. It is a message about how the market sees the AI stack. A correlation that high says investors are treating memory and AI infrastructure as almost the same trade: when one goes up, the other almost always does; when one goes down, the other usually follows. For ETF and index derivative users betting on AI storage and computing power, that has deep implications for allocation, risk management, and how we think about “diversification” inside the AI hardware theme.
AI infrastructure used to be shorthand for compute—GPUs, accelerators, specialized CPUs, networking. Memory was considered an important but secondary detail. A 90% correlation between AI infrastructure indices and memory indicators suggests that distinction is fading. The market is increasingly saying: without memory, there is no AI infrastructure. That linkage is being encoded directly into how products trade.
Correlation at 90%: What It Actually Means
A 90% correlation between an AI infrastructure index (or ETF) and a memory indicator means that, historically over the observed period, their returns moved together most of the time and in similar magnitude. Day by day or month by month, when AI infrastructure hardware rallied, memory sales, pricing, or memory-focused ETFs also tended to rally. When infrastructure sold off, memory usually did too.
This does not mean they are identical. Memory and compute still have their own fundamentals. But from a portfolio and trading perspective, a 90% correlation implies that owning both as “separate” AI hardware bets may not provide much diversification. You are essentially doubling down on one highly connected theme: the capacity to store and move data at high bandwidth for AI workloads.
For ETF and derivative users, that kind of correlation turns AI infrastructure plus memory into one integrated risk factor, not two independent ones.
Why AI Infrastructure and Memory Are So Tightly Linked
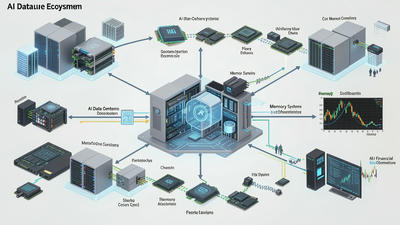
The reason correlation is so high is structural. Modern AI, both training and inference, consumes massive amounts of memory bandwidth and capacity. GPUs and accelerators cannot perform efficiently without fast DRAM, HBM, and related memory technologies. AI data centers are increasingly designed as balanced systems, where compute and memory are co-invested and co‑deployed.
Capital flows reflect that. When hyperscalers announce big AI capex plans, they are not just buying compute; they are also committing to memory, storage, and interconnect. Hardware vendors for compute and memory see orders rise together. As a result, indices and ETFs tracking AI infrastructure and memory components move together. The more AI capex is seen as a unified infrastructure spend, the more the market prices these hardware categories as connected, not independent.
Fundamentally, a 90% correlation is the market’s way of saying: AI infrastructure is as much a memory story as it is a compute story.
Implication 1: Memory Has Become Core AI Beta
The first implication is that memory exposure has effectively become core AI beta. If AI infrastructure and memory indicators move almost in lockstep, owning memory-focused ETFs or indices is not just a side bet—it is central to expressing the AI hardware view.
This matters because many investors historically underweighted memory relative to logic and compute, seeing it as more cyclical and less “innovative.” The high correlation suggests that, in the AI era, memory is no longer peripheral. It is embedded in the infrastructure outcome: if AI hardware does well, memory tends to do well; if AI hardware struggles, memory tends to struggle.
For ETF and derivative users, that means memory-themed products are not just diversifiers—they are core tools for AI exposure.
Implication 2: Limited Diversification Inside AI Hardware
Many investors buy both AI infrastructure ETFs and memory ETFs expecting to diversify within AI hardware. A 90% correlation means that expectation may be misplaced. In terms of short- to medium-term returns, these exposures are very similar. Owning both may increase exposure more than it reduces risk.
True diversification inside AI hardware would require exposures that behave differently—perhaps networking, power and cooling, or broader storage infrastructure that follows different cycles. Memory and compute are currently too tightly bound to act as distinct cushions against each other’s volatility.
From a portfolio construction perspective, this implies that an AI hardware sleeve built solely from infrastructure and memory products is highly concentrated in one risk factor. The diversification benefit is marginal; risk is shared.
Implication 3: Index Derivative Design Must Reflect Connectivity
For index derivatives—futures, options, swaps—linked to AI storage and computing power, a 90% correlation forces designers and users to treat memory and infrastructure indices as heavily interconnected. Hedging a position in an AI infrastructure future with a memory future, for example, may not provide much variance reduction; it may simply reduce net exposure but leave the core driver unchanged.
Complex strategies that assume memory and infrastructure indices move independently will struggle. Instead, derivatives will likely be used to manage aggregate AI hardware risk or to express subtle relative views at the margin (e.g., memory outperforming compute within the same general trend), rather than as fully independent legs.
By 2027, index products and structured strategies will need to explicitly acknowledge this connectivity. The notion of “AI compute vs AI memory” as two separate macro bets will give way to “AI hardware” as a single connected trade with internal relative nuances.
Implication 4: Rotation Signals Need More Refinement
Historically, investors watched rotations between compute-heavy and memory-heavy hardware as signals of cycle phases: memory rallying could indicate a specific inventory and pricing cycle, while compute rallying could reflect different demand dynamics. The high correlation now suggests that simple rotation models need more refinement.
With a 90% correlation, you can still look for relative performance differences—memory slightly outperforming infrastructure or vice versa—but the underlying trend is likely shared. Rotations may be smaller and more tactical. Larger divergences, when they occur, will be more informative precisely because they are rarer.
For ETF and derivative traders, relative trades between AI infrastructure and memory indices will require close attention to fundamentals (pricing, inventories, production plans) rather than relying on correlation to provide a natural hedge. The default state is co‑movement; divergence becomes special, not routine.
Implication 5: Risk Management Must Treat AI Hardware as One Bucket
From a risk management perspective, a 90% correlation means AI infrastructure and memory exposures should be treated as one bucket in risk systems. If both move together most of the time, they share drawdown regimes, peak-to-trough patterns, and volatility clusters.
Risk teams should therefore:
- Aggregate AI infrastructure and memory positions when assessing sector and theme risk.
- Monitor combined exposure relative to overall portfolio risk limits.
- Consider hedging at the aggregate AI hardware level, not just at subcomponent levels.
Treating them separately in risk reports may understate the true concentration. In practice, capital is being put to work against one highly correlated theme: AI hardware capacity.
Implication 6: Market Narrative Is Ahead of Accounting Labels
Another subtle implication is that the market narrative may be ahead of traditional accounting labels. Financial reporting often classifies companies as “memory,” “logic,” “compute,” or “equipment” based on product lines. A 90% correlation between AI infrastructure and memory indicators suggests that, in reality, these segments are being priced as parts of one integrated AI platform.
Investors and analysts may need to update their mental maps. Instead of thinking of memory as a separate semiconductor subsector, the AI era encourages thinking of memory as an integral part of AI infrastructure. ETF and index derivation will reflect that; portfolios will increasingly be built around AI hardware stacks, not around old subsector labels.
This shift has consequences for how investors analyze companies, allocate across subsectors, and design thematic products.
Implication 7: Picking AI Storage vs Compute Is a High-Conviction Play
Given the high correlation, choosing to overweight AI storage versus AI compute becomes a higher-conviction play. You are not moving into a dramatically different risk regime; you are making a nuanced bet within a shared trend. Relative outperformance will depend on specific fundamentals—memory pricing trajectories, HBM adoption curves, supply constraints, and capex timing—not on broad macro differences.
For ETF investors, this means:
- Core AI hardware exposure can be expressed through broad infrastructure ETFs that blend storage and compute.
- Additional tilts toward dedicated memory or compute ETFs should be based on deep analysis, not on an assumption of diversification.
In other words, tilting between AI storage and computing power is more akin to sector rotation within a single theme than to moving between distinct asset classes.
What Investors Should Do With This Knowledge
Investors using AI storage and computing power ETFs and index derivatives should interpret the 90% correlation as a warning and an opportunity:
- Warning: Do not assume memory and AI infrastructure are independent exposures. Position sizing, hedging, and diversification must recognize their shared behavior.
- Opportunity: Use broad AI hardware products as core exposure, and memory or compute-specific products to fine-tune allocations based on detailed cycle analysis.
Strategically, the best approach may be to treat AI hardware as a unified theme with sub-tilts, not as two separate themes. Tactical trades can still exploit relative performance, but the default expectation should be co-movement.
For derivative users, this implies hedging and arbitrage strategies should be built around the aggregate AI hardware risk factor, rather than assuming low correlation between memory and infrastructure indices. Tools that reference the combined theme may offer simpler and more robust ways to manage exposure.
Conclusion
A 90% correlation between AI infrastructure and memory indicators tells a clear story: in the current AI era, memory is no longer a secondary consideration. It has become inseparable from the infrastructure it supports. For ETF and index derivative investors, that means AI storage and computing power should be treated as one tightly linked risk factor, not two independent bets.
This understanding reshapes how we build AI hardware sleeves, design products, manage risk, and interpret rotations. Memory-themed ETFs are not just diversifiers; they are core AI exposure. AI infrastructure products are not just compute; they are implicitly memory as well. The market has already encoded that reality in its correlations. The question for investors is whether their strategies and risk models have caught up.